
What to Do After a Car Accident: The Insurance Claim Process
Steps to protect yourself, document the scene, and file a claim with confidence.
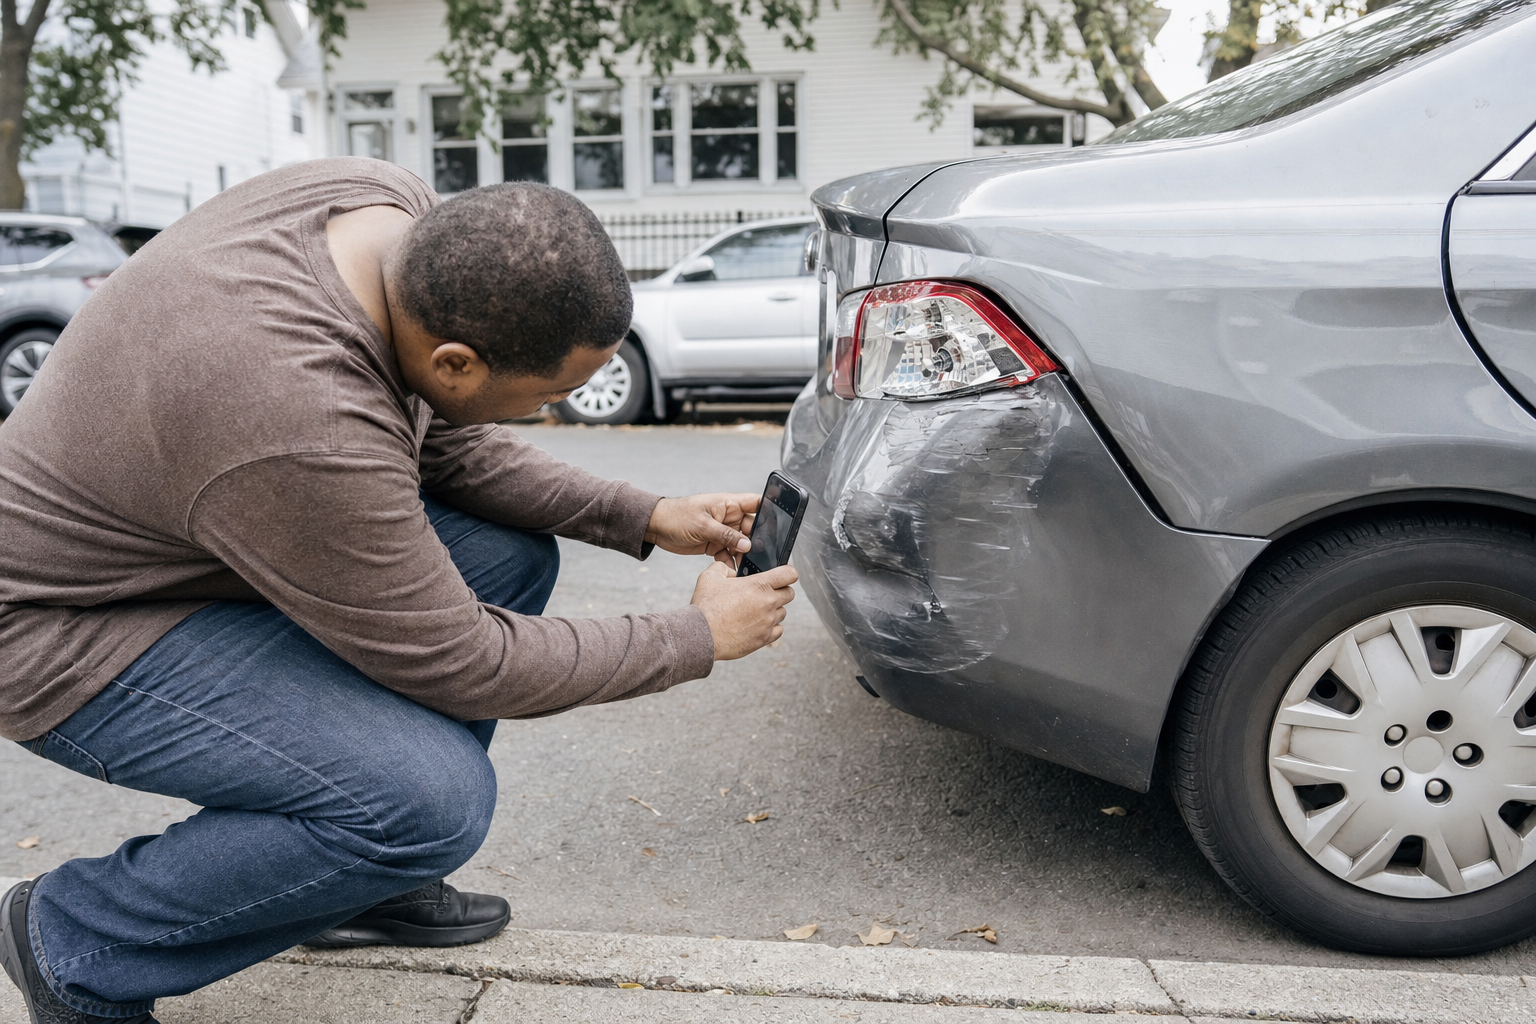
A car accident can happen in seconds and leave you uncertain about what to do next.
The car insurance claim process starts the moment the collision occurs.
Thorough documentation at the scene and prompt communication with your insurer are practical steps that can support your claim.
This guide walks through each step, from securing the scene and exchanging information to notifying your insurer and working with a claims adjuster.
Because reporting requirements, deadlines, and claim rules vary by state and policy, always confirm the specific rules that apply to your situation with your insurer and your state’s insurance department.
Safety and documentation come before everything else.
Practical steps include gathering evidence at the scene and notifying your insurer promptly, but your first responsibility is to protect yourself and others from further harm.
Secure the Scene and Check for Injuries
Do not leave the scene of the accident.
If it is safe to do so, move your vehicle out of traffic to prevent additional collisions.
Turn off the engine and check yourself and any passengers for injuries.
Call 911 when anyone is injured, when you need police assistance, or when an emergency exists.
Accident-reporting requirements vary by state and may depend on the severity of the incident.
Check with your state department of motor vehicles or insurance department to confirm whether a police report or other official report is required in your situation.
Exchange Information with the Other Driver
Collect the other driver’s full name, phone number, address, driver’s license number, license-plate number, vehicle make and model, and insurance company and policy number.
Provide your own information in return.
Avoid discussing fault, making unsupported admissions, or speculating about what happened.
Stick to factual details and cooperate with police when they arrive.
Document Everything at the Scene
Take photographs or video of all vehicle damage, the surrounding area, road conditions, traffic signs, skid marks, property damage, and license plates.
If there are visible injuries and it is appropriate to do so, photograph those as well.
Write down the names and contact information of any witnesses.
Make notes about what you remember while the details are still fresh, including the time, weather, and sequence of events.
This documentation becomes part of the evidence the claims adjuster will review during the car insurance claim process.
Report the Accident When Required
Check your state’s DMV website or contact your local police department to confirm whether you are required to file a crash report with the police or the department of motor vehicles.
Reporting requirements are jurisdiction-specific and typically depend on factors such as injury, death, or property damage above a threshold.
A police report may also be requested by your insurer and can support your claim.
Notify Your Insurer Promptly
Contact your insurance company as soon as possible after the accident, even if you are not sure whether you want to file a claim.
Notification practices vary by insurer and state, so confirm with your insurer how reporting the incident relates to opening a formal claim and whether notification may affect your premium.
Your insurer can explain your coverage, deductibles, and next steps.
You can reach your insurer by phone, through its website or mobile app, or by contacting your agent.
Provide the date, time, and location of the accident, a description of what happened, your policy number, the other driver’s information, the police report number if available, photographs, and witness contact details.
Understand the Claims Adjuster’s Role
Once you open a claim, a claims adjuster will be assigned to investigate.
The adjuster reviews available evidence, including vehicle damage, accident reports, and documentation you provide, to assess the claim and settlement.
Coverage and fault determinations depend on your policy terms, the facts of the accident, and applicable state law.
Cooperate fully with the adjuster and provide any additional information or documentation requested.
First-Party vs. Third-Party Claims
The car insurance claim process can follow two different paths depending on fault, state law, and the coverage you purchased.
| Claim Type | Description |
|---|---|
| First-party claim | You file with your own insurer under collision, comprehensive, personal injury protection, or another applicable coverage you purchased. |
| Third-party claim | You file with the other driver’s insurer when that driver is allegedly at fault and their liability coverage may apply, subject to state law and policy terms. |
Which route is available depends on state law, fault determination, and the coverages in force.
Your insurer can explain which option applies to your situation.
Follow the Repair and Settlement Process
Temporary repairs necessary to prevent further damage may be appropriate, but generally do not begin permanent repairs until you notify your insurer and follow its inspection or authorization instructions.
Permanent repairs made before the insurer has inspected or documented the loss may not be covered.
The insurer may send an appraiser to inspect the vehicle or request repair estimates.
The specific process depends on your policy and the insurer’s procedures.
Keep all receipts, estimates, medical bills, rental-car invoices, and correspondence related to the claim.
If the vehicle is declared a total loss, the insurer will offer a settlement based on the applicable coverage, policy terms, vehicle valuation, your deductible, and any salvage considerations under state law.
What to Do If Your Claim Is Denied
A denial does not necessarily mean the end of the car insurance claim process.
Ask the insurer to provide the reason for the denial in writing.
Review your policy carefully and request clarification or reconsideration if you believe the denial is incorrect.
Check with your insurer about its complaint or appeal procedures.
If the dispute is not resolved, contact your state insurance department for assistance.
The remedies available to you depend on state law, your insurer’s procedures, the policy language, and the facts of your case.
Understanding the car insurance claim process before an accident happens can reduce stress and help you protect your rights when it matters most.
Review your policy now, know what coverage you have, and save your insurer’s contact information where you can find it quickly.
If an accident does occur, prioritize safety, document thoroughly, and communicate promptly with your insurer and the appropriate state agencies.
* Accident-reporting requirements, claim deadlines, and coverage rules vary by state and policy. Confirm the current rules with your insurer and your state insurance department.